
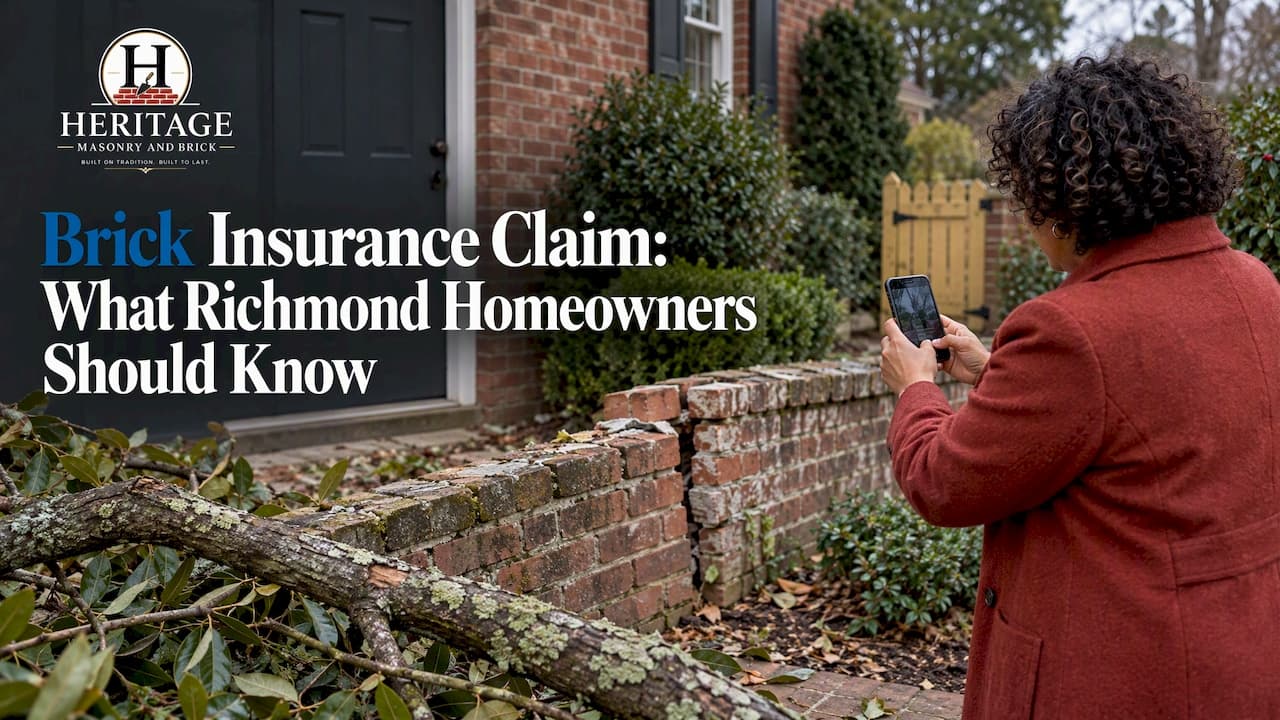
Homeowners insurance pays for brick damage when a covered event causes it, such as a fire, a windstorm, hail or a vehicle striking the wall. It does not pay for brick that has simply aged, worn out or been neglected. Crumbling joints, spalling faces and water that has seeped in over the years are normally treated as maintenance. If you own brick in Richmond, Virginia, the first step is to work out which kind of damage you have. The second is to document it well before anyone starts repairs.
This guide explains what is usually covered and what is not. It also covers how to build a claim file, how to work with an adjuster, and how Richmond's historic districts and the right mortar affect the repair afterward.
TL;DR
- Insurance generally covers sudden, covered events such as fire, wind and hail. It does not cover wear and tear or maintenance problems.
- Photograph everything, keep receipts, and write down every call with your insurer before repairs begin.
- Get your own written repair estimate from an experienced mason so you can compare it with the adjuster's figure.
- In Richmond's Old and Historic Districts, exterior changes may need city review, so match the original brick and mortar.
- Repairs that are not covered still need to be done, and early repointing is far cheaper than rebuilding a wall.
Table of Contents
- What homeowners insurance usually covers for brick
- Brick walls, chimneys, steps and detached structures
- What to do right after you find brick damage
- Building your claim file
- Working with the adjuster
- Deadlines, denials and appeals in Virginia
- Historic districts and code upgrades in Richmond
- Why the brick and mortar you choose matter
- When insurance will not pay
- Our perspective
- Get your brick assessed in Richmond
- FAQ
- Sources
What homeowners insurance usually covers for brick
Standard homeowners policies protect against sudden, unpredictable events. Farmers' guide to covered perils lists fire, windstorm, hail and vandalism as typically covered. It lists flooding, earthquakes, sewer backup, wear and tear and maintenance issues as typically excluded. Whether a peril is covered also depends on whether your policy is named-perils or open-perils, so read yours.
The National Association of Insurance Commissioners (NAIC) puts the principle plainly. Its consumer guide to home insurance explains that a homeowners policy is not a maintenance contract and does not pay to repair items that simply wear out.
For brick, this plays out in a few ways:
- Likely covered: a tree limb or storm debris that cracks a wall, hail damage, a vehicle that hits a garden wall, or fire and smoke damage to a chimney.
- Often disputed: water damage that began as a sudden event but looks like long-term seepage, such as a failed gutter that soaked a wall.
- Usually not covered: eroded mortar joints, spalling faces, efflorescence, settling cracks, and general age-related deterioration.
Forbes Advisor adds that standard policies commonly exclude floods, earthquakes, mold and earth movement such as settling, unless you add specific coverage. Settling cracks in older Richmond brick are common, so know that exclusion before you file.
One point works in your favor. The NAIC notes that premiums for brick or masonry homes are often lower than for wood-frame homes, which reflects the perceived durability of the material. Well-kept brick is a good asset to protect.
Brick walls, chimneys, steps and detached structures
Coverage depends on which part of the property is damaged.
The house itself. Brick veneer or structural brick walls are part of the dwelling, so covered damage falls under your main dwelling coverage.
Detached structures. Garden walls, a detached garage or a freestanding brick structure on your lot usually fall under Coverage B. The NAIC defines Coverage B as protection for detached structures on the residence premises when an insured peril causes the damage. Check your policy's limit for this coverage, because it is often a fraction of the dwelling limit.
Chimneys. Storm and fire damage to a chimney can be covered. A chimney that leaks because the crown has cracked and the mortar has eroded over decades is usually a maintenance issue. Our chimney repair work covers both situations, whichever your insurer decides.
Steps, walkways, patios and retaining walls. These are the hardest to claim. Freeze and thaw cycles, tree roots and drainage failures are slow processes, and insurers rarely treat them as sudden events. A retaining wall pushed over by a fallen tree is a different story from one that has bowed over fifteen years. For the second case, see our guide to brick retaining wall repair.
Foundations. Brick foundation damage from earth movement is a common exclusion. Our guide to brick foundation repair explains how to tell cosmetic joint wear from structural movement.

What to do right after you find brick damage
The moves below protect both your safety and your claim. They come from standard consumer guidance and from what we see on the job.
- Stay clear of unstable masonry. Keep people and pets away from leaning walls, loose chimney bricks and cracked steps. If a chimney or wall looks ready to fall, call a mason or the fire department's non-emergency line for advice before anyone goes near it.
- Photograph and video the damage. Take wide shots showing location and close-ups showing the cracks, missing bricks and displaced mortar. Shoot from several angles and include something for scale.
- Prevent further damage. A tarp over an exposed chimney or a board over a broken section is reasonable. Insurers generally expect you to protect the property, and the Virginia State Corporation Commission (SCC) tells homeowners to keep receipts for cleanup and temporary repairs.
- Save loose pieces. Broken bricks and mortar crumbs help a mason identify the original brick and mix, and they show the adjuster what failed.
- Call your agent or insurer promptly. Ask about claim forms and the process. Do this before you hire anyone to start work.
If a burst pipe or other water event caused the brick damage, the same habits apply. A plumbing company's advice on taking insurer-ready photos shows how much a clear photo record helps later.
Building your claim file
A well-organized file makes the claim faster and harder to dispute. The SCC's guidance for insured homeowners says to photograph the damage and keep receipts for cleanup and temporary repairs. It also says to record call dates, names and what was discussed. The NAIC adds that a household inventory with photos and receipts helps support a claim.
For brick, a strong file includes:
| Item | Why it helps |
|---|---|
| Dated photos and video | Shows condition and extent at discovery |
| Photos from before the damage | Proves the wall was sound, such as listing photos or old renovation shots |
| Weather records or news reports | Links the damage to a storm date |
| Call log | Names, dates and what each person said |
| Receipts for temporary protection | Supports reimbursement requests |
| Written mason's estimate | A second opinion on scope and cost |
| Maintenance records | Shows that the wall was cared for |
Maintenance records matter more than most owners expect. If you repointed ten years ago and kept the invoice, it helps show that the damage came from an event and not from neglect.
Working with the adjuster
According to the SCC, after you report a loss the company assigns a representative to inspect the damage and prepare an estimate. The SCC also advises homeowners to get written estimates before repairs begin.
A few practical points make that inspection go better:
- Be there. Walk the adjuster around the whole property, not just the area you reported.
- Point out brick-specific issues. Adjusters are generalists. Tell them if the mortar is soft lime, if the brick is historic, or if the wall is a double-wythe or veneer.
- Get the estimate in writing, with line items, not just a total.
- Compare it with a mason's scope. A pricing sheet built for modern brick and Portland cement mortar can miss the cost of matching old brick and lime mortar. If the figures differ, send your mason's written estimate to the insurer and ask them to reconcile it.
We provide free estimates. Our masonry estimate checklist and worked takeoff shows what a clear scope looks like, which is useful when comparing it with an adjuster's numbers.
Deadlines, denials and appeals in Virginia
Read the claim section of your policy for notice and filing deadlines, because they vary by company and policy. Report damage promptly even if you are unsure it is covered. Late notice can hand an insurer a reason to deny.
If a claim is denied or underpaid, start with the insurer in writing. Ask for the specific policy language behind the decision. Virginia's regulator, the SCC Bureau of Insurance, reviews how companies handle claims. In one market conduct examination of an insurer's 2020 Virginia homeowner claims, the Bureau found failures to disclose pertinent policy benefits and to give reasonable explanations for denials. That is a good reason to insist on a clear written explanation.
Options after a denial typically include a re-inspection with your mason's estimate, an appraisal for disagreements about the amount of loss, and a complaint to the Bureau of Insurance. For a plain-language walk through those routes and their deadlines, see this Virginia claim dispute guide. For coverage questions on a specific policy, talk to your agent or a licensed Virginia attorney.
Historic districts and code upgrades in Richmond
Richmond has many brick homes in the Fan District, Museum District, Monument Avenue area and other older neighborhoods. Repairs there can involve more than insurance.
The city's Commission of Architectural Review (CAR) is the official historic preservation body. It reviews exterior changes in the Old and Historic Districts and issues Certificates of Appropriateness for projects it considers appropriate. Its decisions rest on the Secretary of the Interior's Standards and the Richmond Old & Historic Districts Handbook and Design Review Guidelines. If you live in one of those districts, check with city planning staff before you start exterior brickwork, so that an insured repair does not stall over approvals.

A related policy feature is Ordinance or Law coverage. The NAIC explains that it pays the extra expense to rebuild in compliance with building codes and other laws that did not exist when the home was built. Ask your agent whether your policy includes it. It matters most for older Richmond houses where a rebuilt chimney or wall must meet today's requirements.
Property managers face a related paperwork issue. Managing repair contractors on commercial or multifamily brick means checking that each one carries the right coverage. These vendor insurance requirements for property managers are a useful checklist for that part of the job.
Why the brick and mortar you choose matter
A claim pays for repair, but how the repair is done decides how long it lasts. Older Richmond brick was laid with lime-based mortar. Lime mortar is softer and more flexible than modern Portland cement mortar. In a traditional wall it is meant to be the sacrificial part, the joint that takes the wear so the brick does not. Hard cement mortar packed into old joints can trap moisture and push the stress onto the brick faces, and that is one reason walls start spalling.
That is why our repairs follow the traditional method:
- Match the brick. Old brick varies in color, size, texture and hardness. We match what is on the wall instead of dropping in modern replacements. See our guide to matching old brick.
- Match the mortar. We use lime mortar mixes matched to the existing joints in color, tooling and strength, so new work blends in and the wall can still breathe.
- Cut out properly. Failed mortar is removed to a proper depth by hand or with care, so new mortar bonds and does not just sit on the surface.
- Fix the cause. Gutters, grading, flashing and chimney crowns get checked, because water is behind most brick failures.
Our page on repointing and tuckpointing explains the process. If faces are flaking, read whether spalling brick can be repaired or needs replacement. For crawl spaces, see how to inspect brick piers before repointing.
When insurance will not pay
Most brick problems we see in Richmond are not insurance events. They are water, age and freeze-thaw wear. That does not mean you should wait. Eroded joints let water in, and water is what turns a small repointing job into a rebuild. Acting early costs less than waiting for a wall to fail.
Before hiring anyone for work insurance will not cover, use our five-point masonry contractor checklist. For more general reading, our masonry advice page covers common questions.
Our perspective
We have worked on brick in and around Richmond for over 25 years, and the same story repeats. A homeowner sees a crack or a crumbling joint, hopes it is an insurance matter, and finds out it is not. The better approach is to know where you stand before you call.
If a storm, fire or impact caused the damage, document it, file promptly and bring a written mason's estimate to the conversation. If it is age and water, plan the repair on your own terms, and do it once, with the right materials.
The right materials are the whole point. Old Richmond brick was built to work with lime mortar. Matching the existing brick and mortar keeps the wall sound and keeps the look of the house. We offer a 5-year guarantee on materials and workmanship, no deposits, and payment on completion, because we expect our repairs to last for decades.
Thomas
Get your brick assessed in Richmond
Whether you are preparing a claim or paying for the repair yourself, a clear written scope helps. We repair brick on homes and businesses across Richmond, Virginia, including historic neighborhoods. Our work covers brick repair, lime mortar repointing, chimneys and structural masonry repairs. Estimates are free. Call 804-324-6304 today.
We match your existing brick and mortar, and the work carries a 5-year guarantee on materials and workmanship. There is no deposit, and you pay on completion.
FAQ
Does homeowners insurance cover cracked brick?
Only if a covered event caused the crack, such as a storm, fire or impact. Cracks from settling, earth movement or age are commonly excluded, as the NAIC and Forbes Advisor guidance above describes. Your policy wording decides, so ask your insurer to explain the cause it relied on.
Should I get a mason's estimate before the adjuster visits?
Yes, if you can arrange it. A written estimate from a mason who works with historic brick shows what matching the brick and lime mortar takes. The SCC advises getting written estimates before repairs begin, and a second figure gives you something to compare with the insurer's.
Is a leaking chimney covered?
It depends on the cause. Storm or fire damage can be covered, while a chimney that leaks because the crown and mortar wore out over time is usually a maintenance item. Document it either way and have a mason inspect it.
Do I need city approval to repair brick in a Richmond historic district?
Often, yes. Richmond's Commission of Architectural Review reviews exterior changes in the Old and Historic Districts. Contact city planning staff before you start work to confirm whether your repair needs a Certificate of Appropriateness.
Sources
- Farmers: What Perils Are Covered by Homeowners Insurance?
- NAIC: A Consumer's Guide to Home Insurance
- Forbes Advisor: What Does Homeowners Insurance Cover?
- NAIC: Homeowners Market Data Call definitions
- Virginia SCC: Disaster Strikes Insured Homeowners Loss
- Virginia SCC: Market Conduct Examination Report
- NAIC: Homeowners Insurance
- City of Richmond: Commission of Architectural Review
- Virginia home insurance claim disputes guide
- Burst pipe: what to do and insurer-ready photos
- Vendor insurance requirements for property managers